
Virtual Assets in Kenyan Banking: Inside The Kenyan Wall Street’s (TKWS) Board of Trailblazers Roundtable


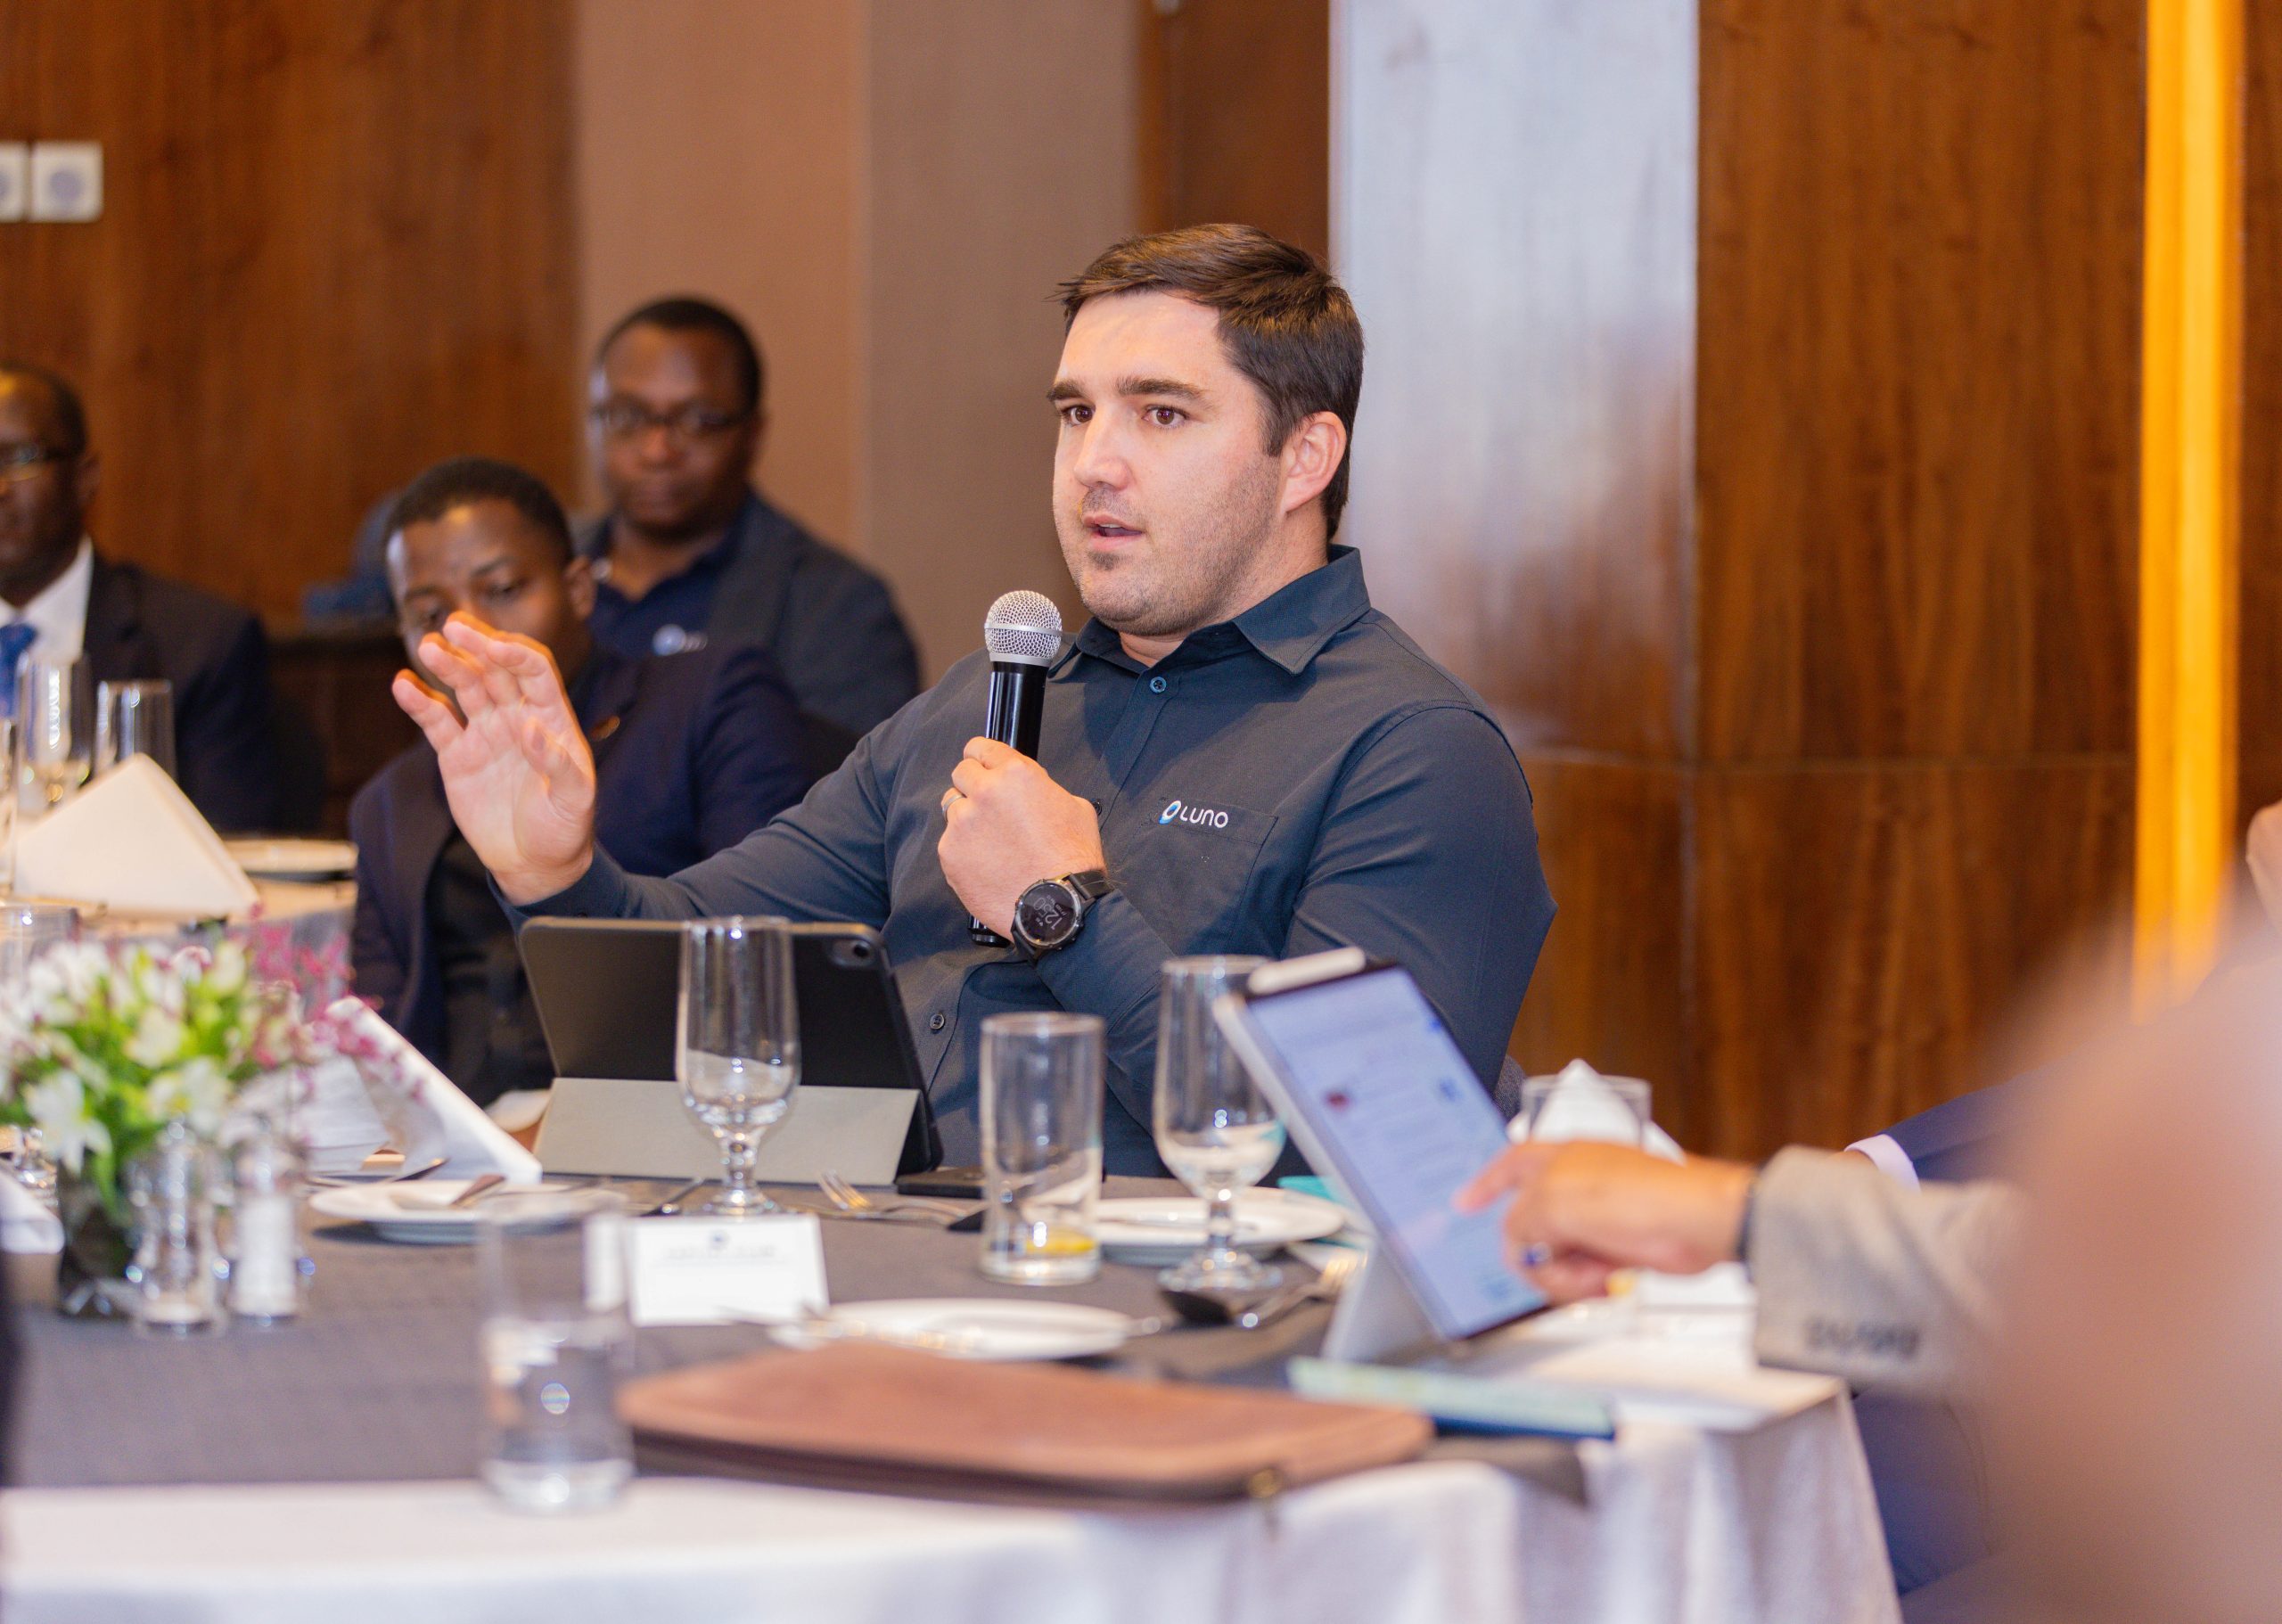
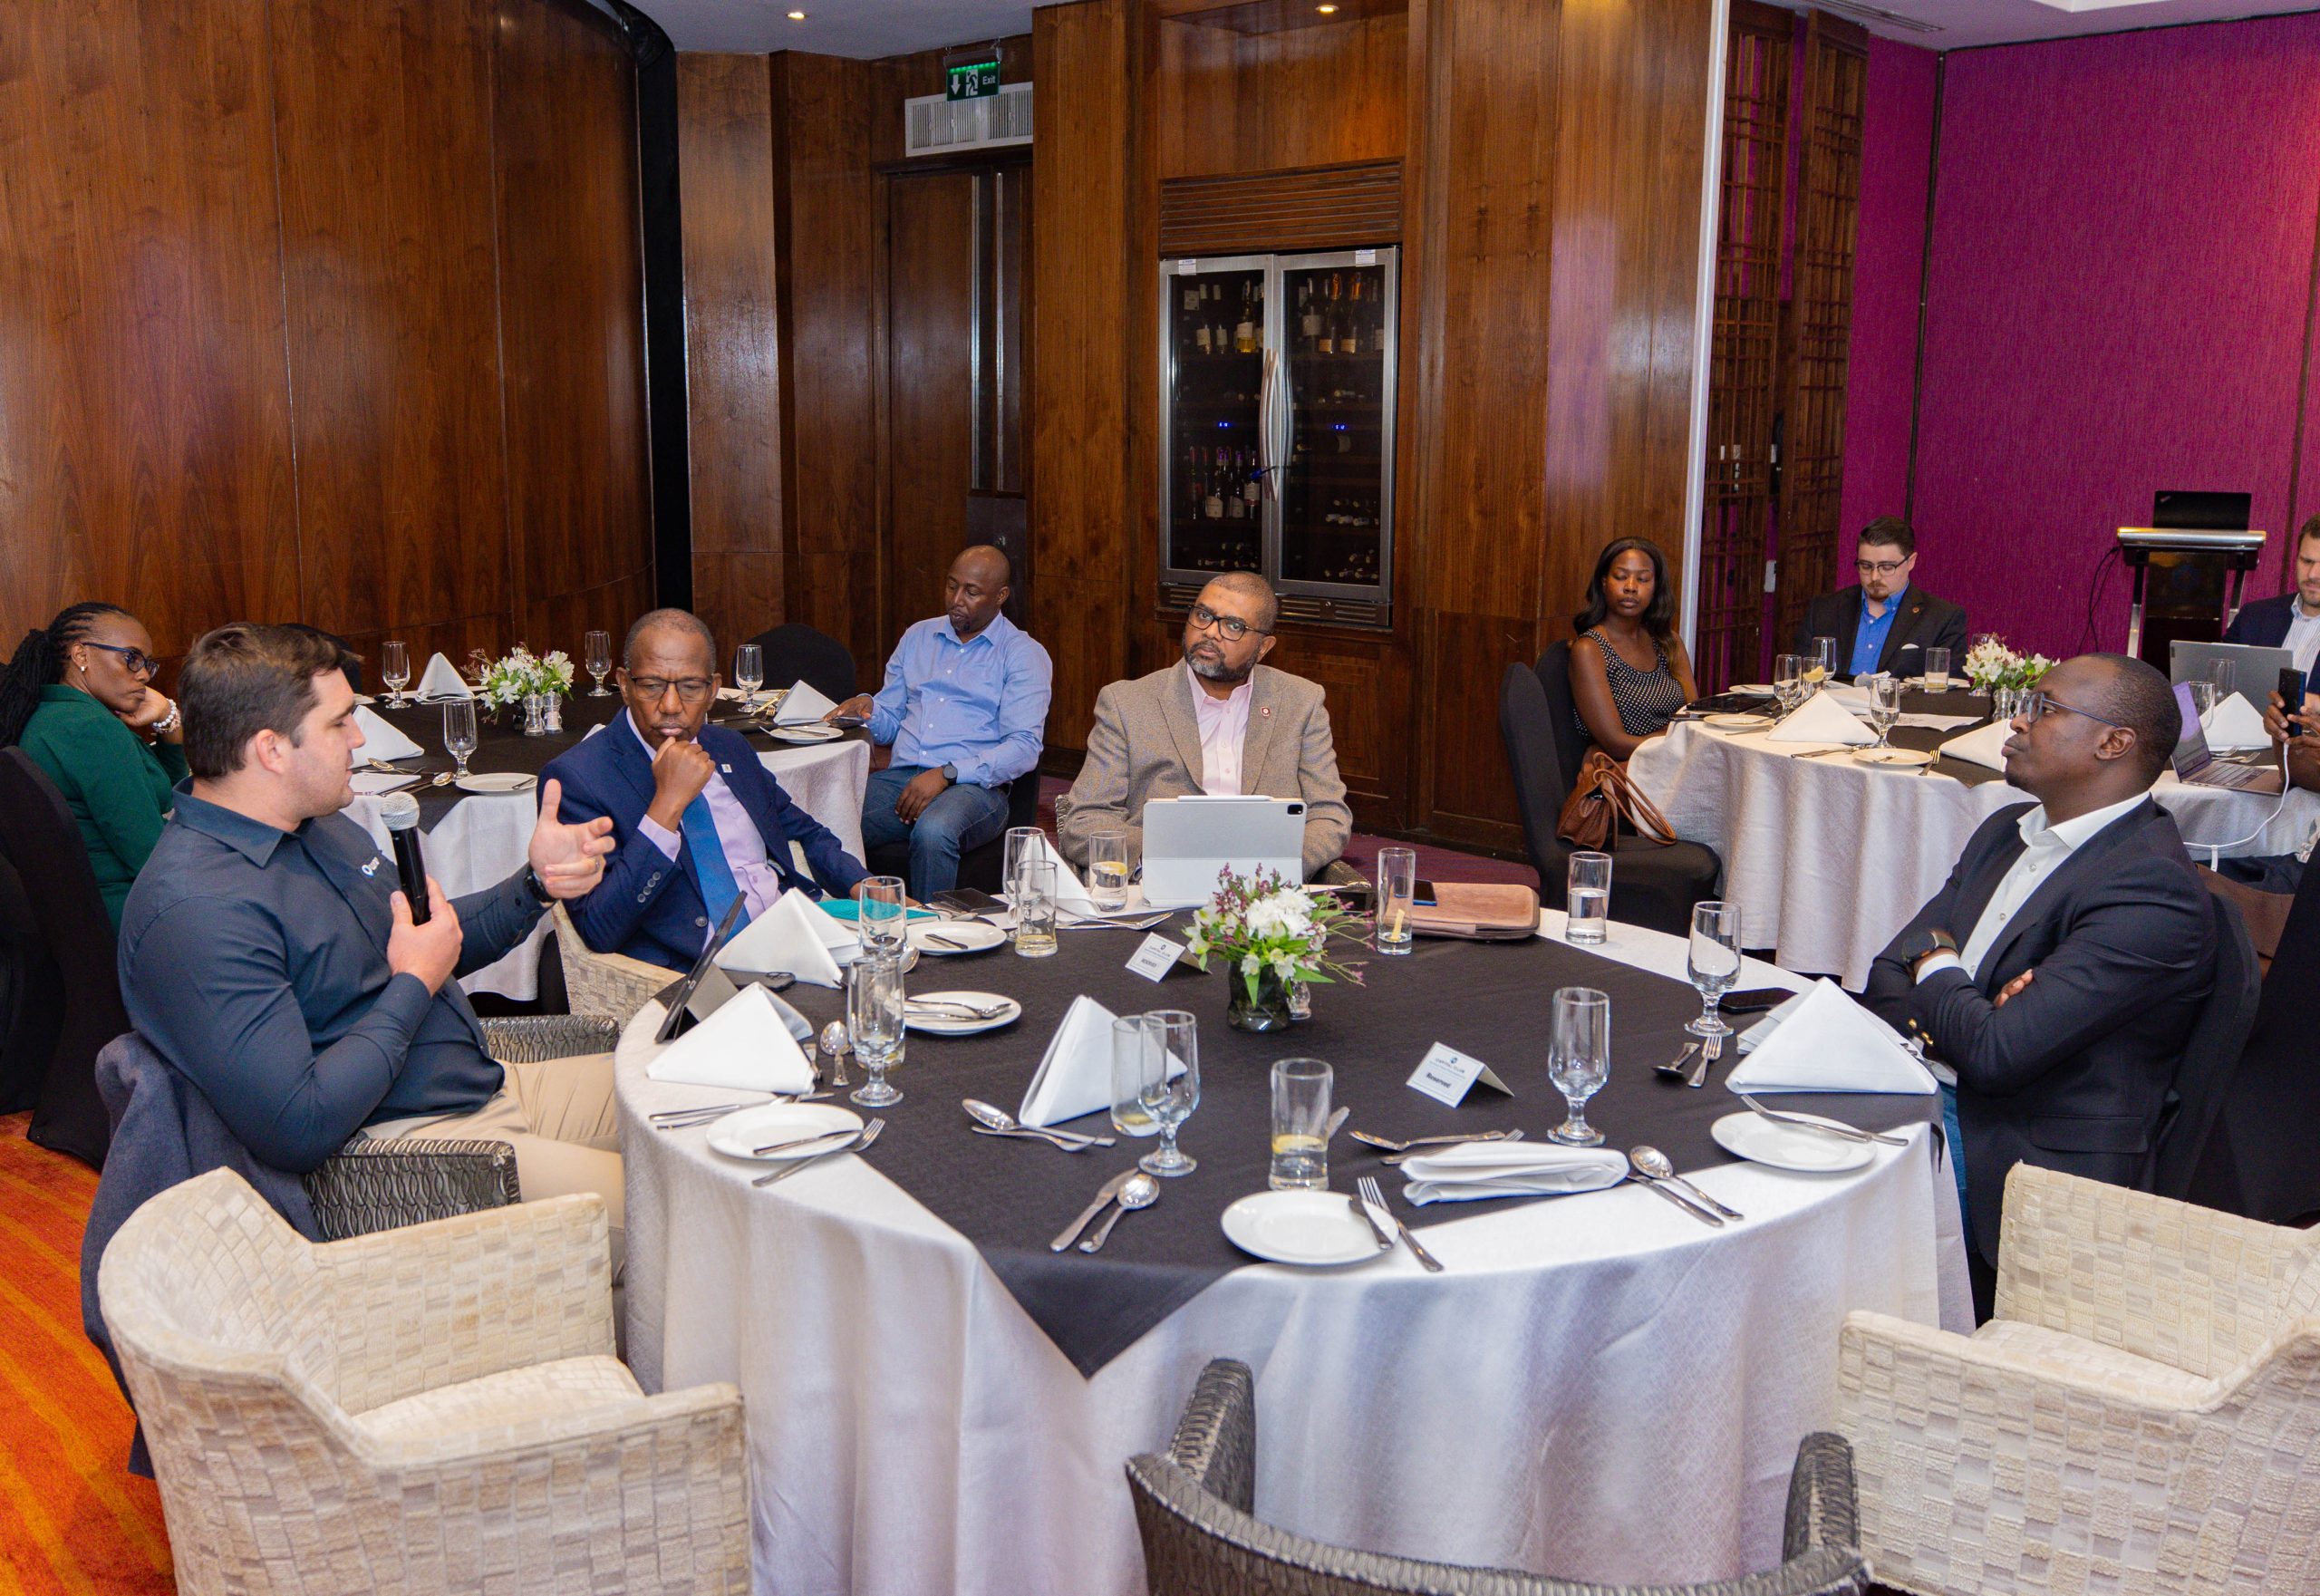
This afternoon at the Capital Club East Africa, on the sidelines of the Africa Tech Summit in Nairobi, I sat in a room where Kenya’s virtual assets future was being negotiated in real time. It wasn’t a conference ballroom, it wasn’t a keynote circus, and there was no stage; just a circle of regulators, bankers, fintech founders, and ecosystem operators in genuine dialogue.
The Kenyan Wall Street’s (TKWS) Board of Trailblazers is designed exactly for this kind of moment – an executive-level roundtable where the people who actually make decisions show up, argue, align, and leave with action items, not just selfies. With Kenya’s Virtual Asset Service Providers Act, 2025 (VASP Act) now law and detailed regulations expected within weeks, the theme – “Virtual Assets in Banking” – could not be more timely.
Why This Roundtable, Why Now?
Kenya has just joined the growing list of countries with a clear legal framework for virtual assets, via the VASP Act, 2025, which licenses and regulates exchanges, custodians, and other VASPs while plugging them into our AML/CFT architecture. The Act gives authorities powers to license, supervise and enforce against VASPs, and obliges them to protect customer assets, maintain capital, and implement robust cybersecurity and governance.
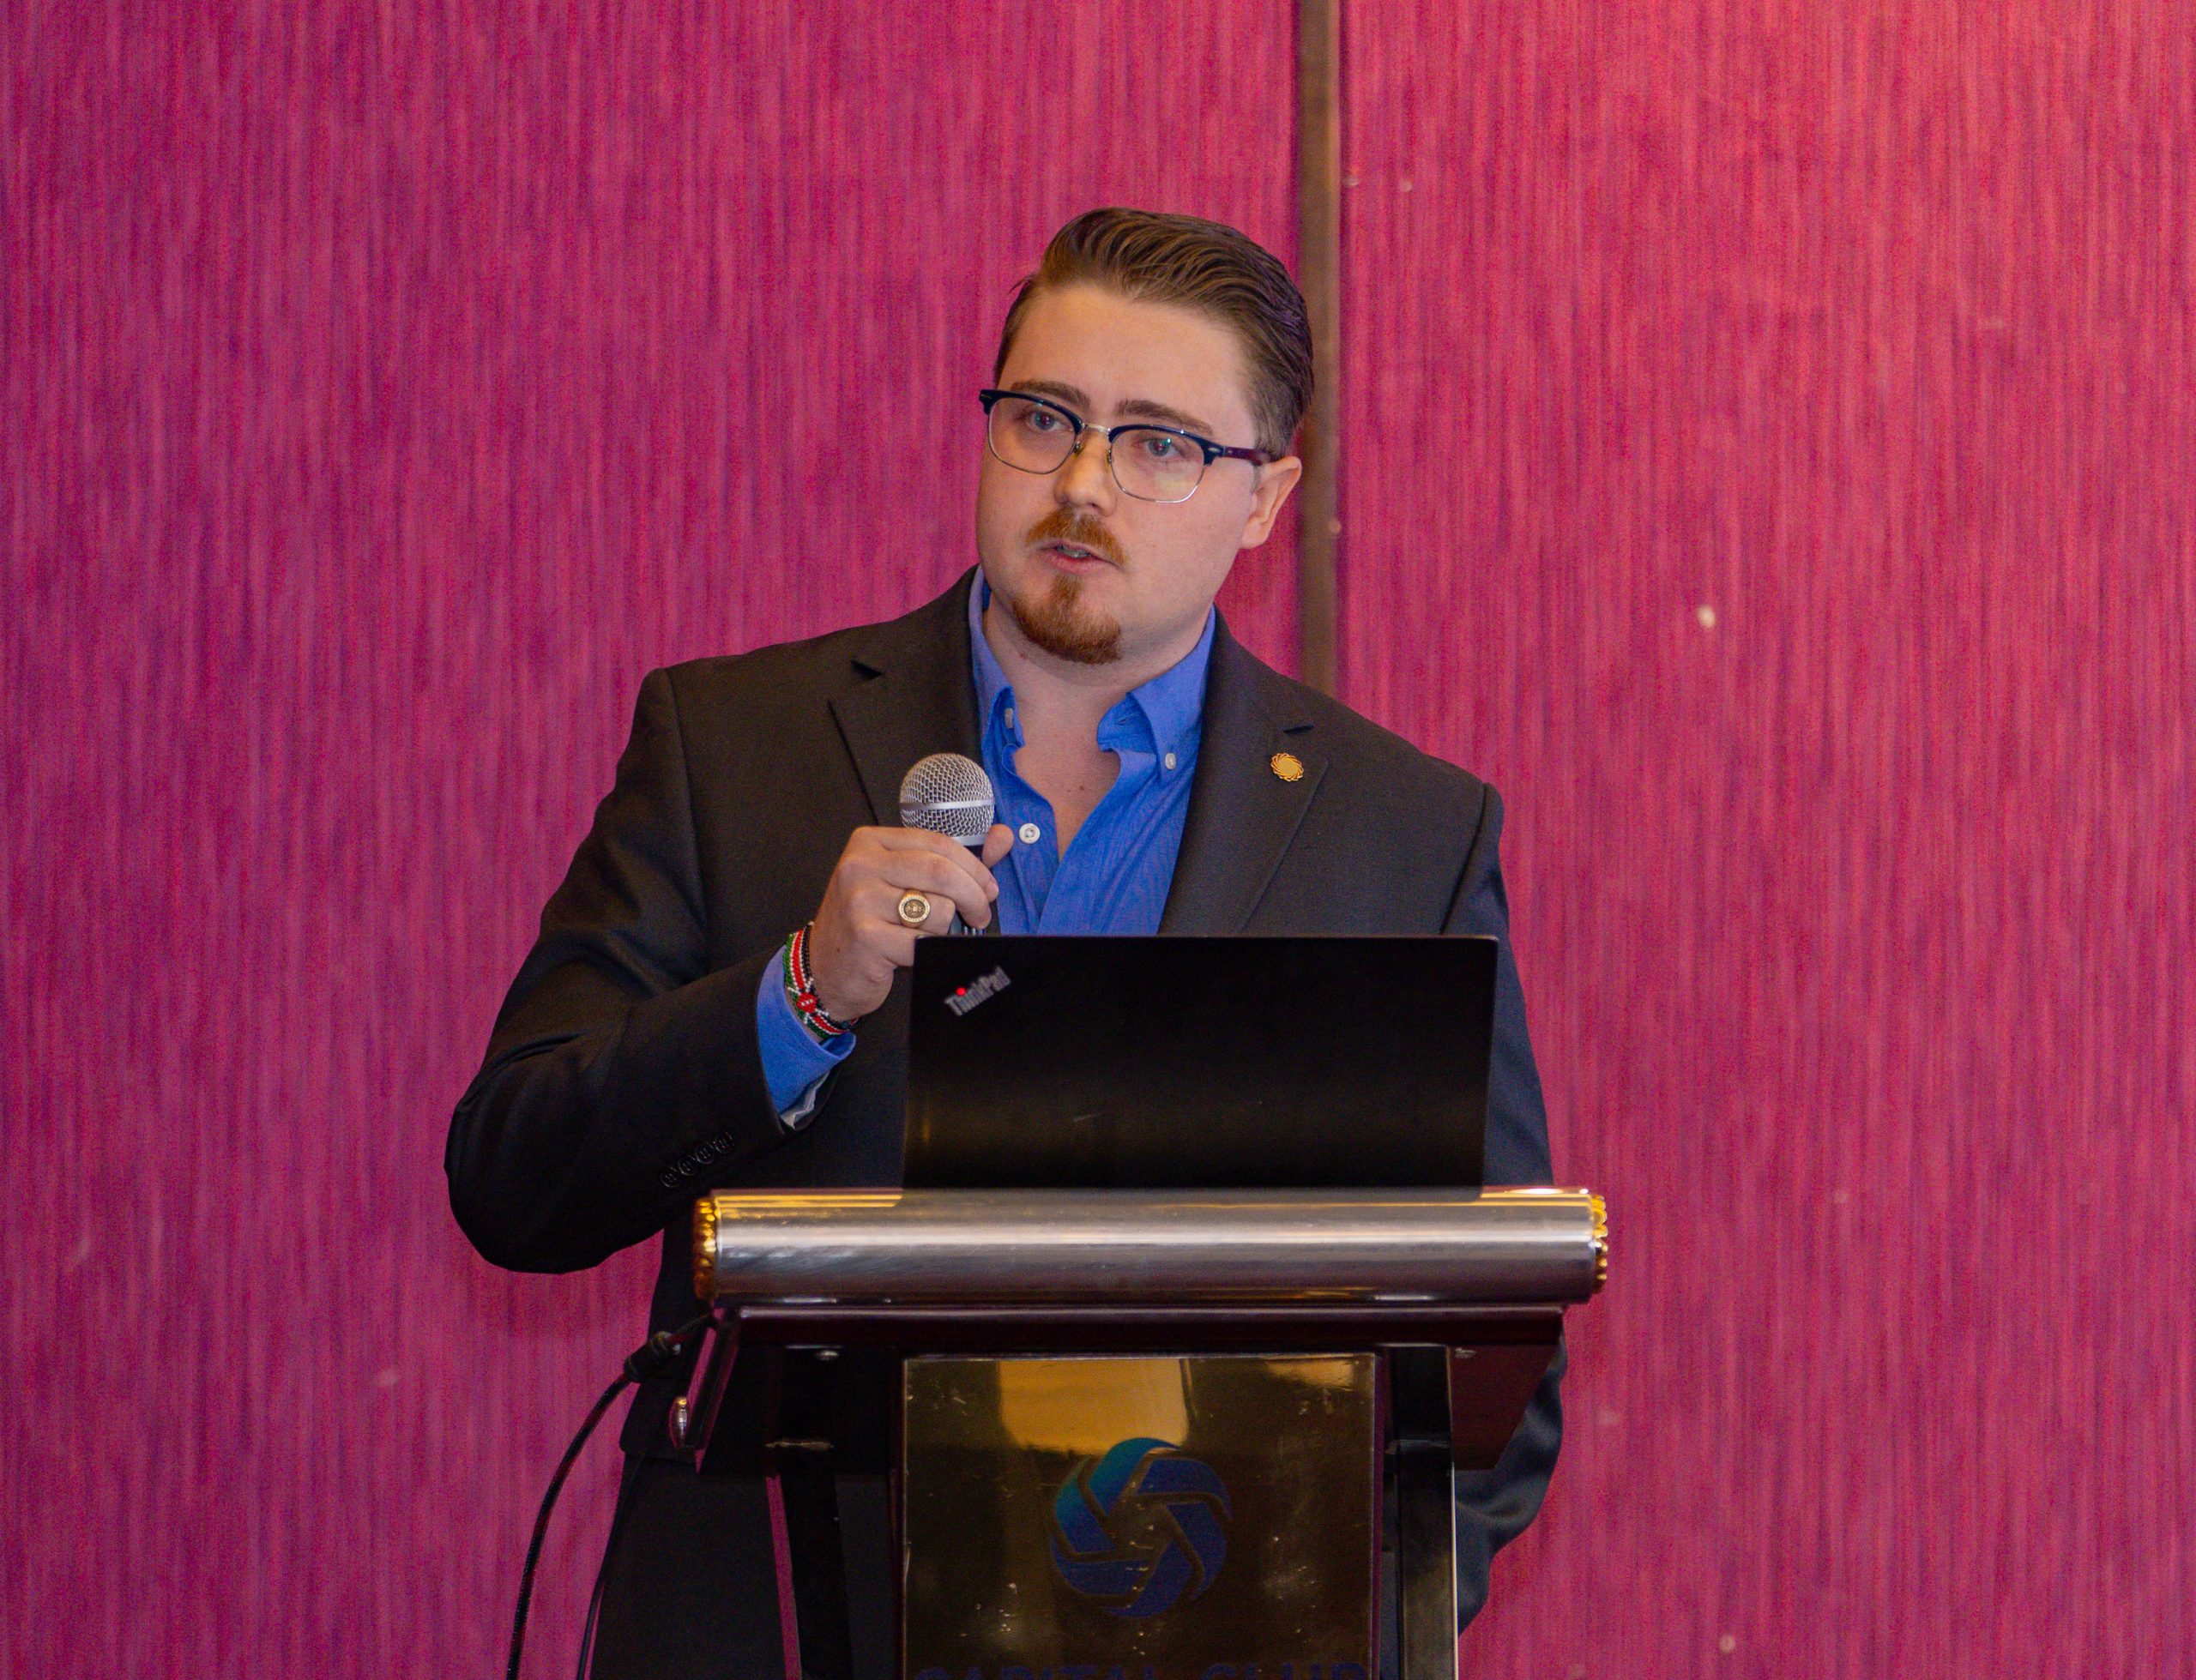
Andrew Barden, CEO of The Kenyan Wall Street, captured the intent perfectly:
“This event today is a little bit different from anything you’ve probably seen here in the local ecosystem… There’s no stage here… The concept [was], wouldn’t I want to be a fly on the wall in that room? Wouldn’t I want to overhear that conversation and take part in that?”
Then he raised the stakes:
“The trailblazers in this room are the ones who will decide whether Kenya remains a follower or becomes the definitive hub of regulated digital finance in Africa.”
That’s why this wasn’t just another panel. It was a working session with concrete action items.
Who Was in the Room – and Why It Mattered
Ali Hussein, digital transformation leader, fintech advocate, and publisher of AliTalksTech, guided the conversation with his usual mix of humour and hard questions. Early on, he reminded everyone that the on‑chain shift is already mainstream:
“Major institutions are moving on‑chain… Larry Fink, CEO of BlackRock, [said] the next generation of securities will be tokenized… The trillion dollar question is, how many African financial institutions are starting to move on?”
The panel
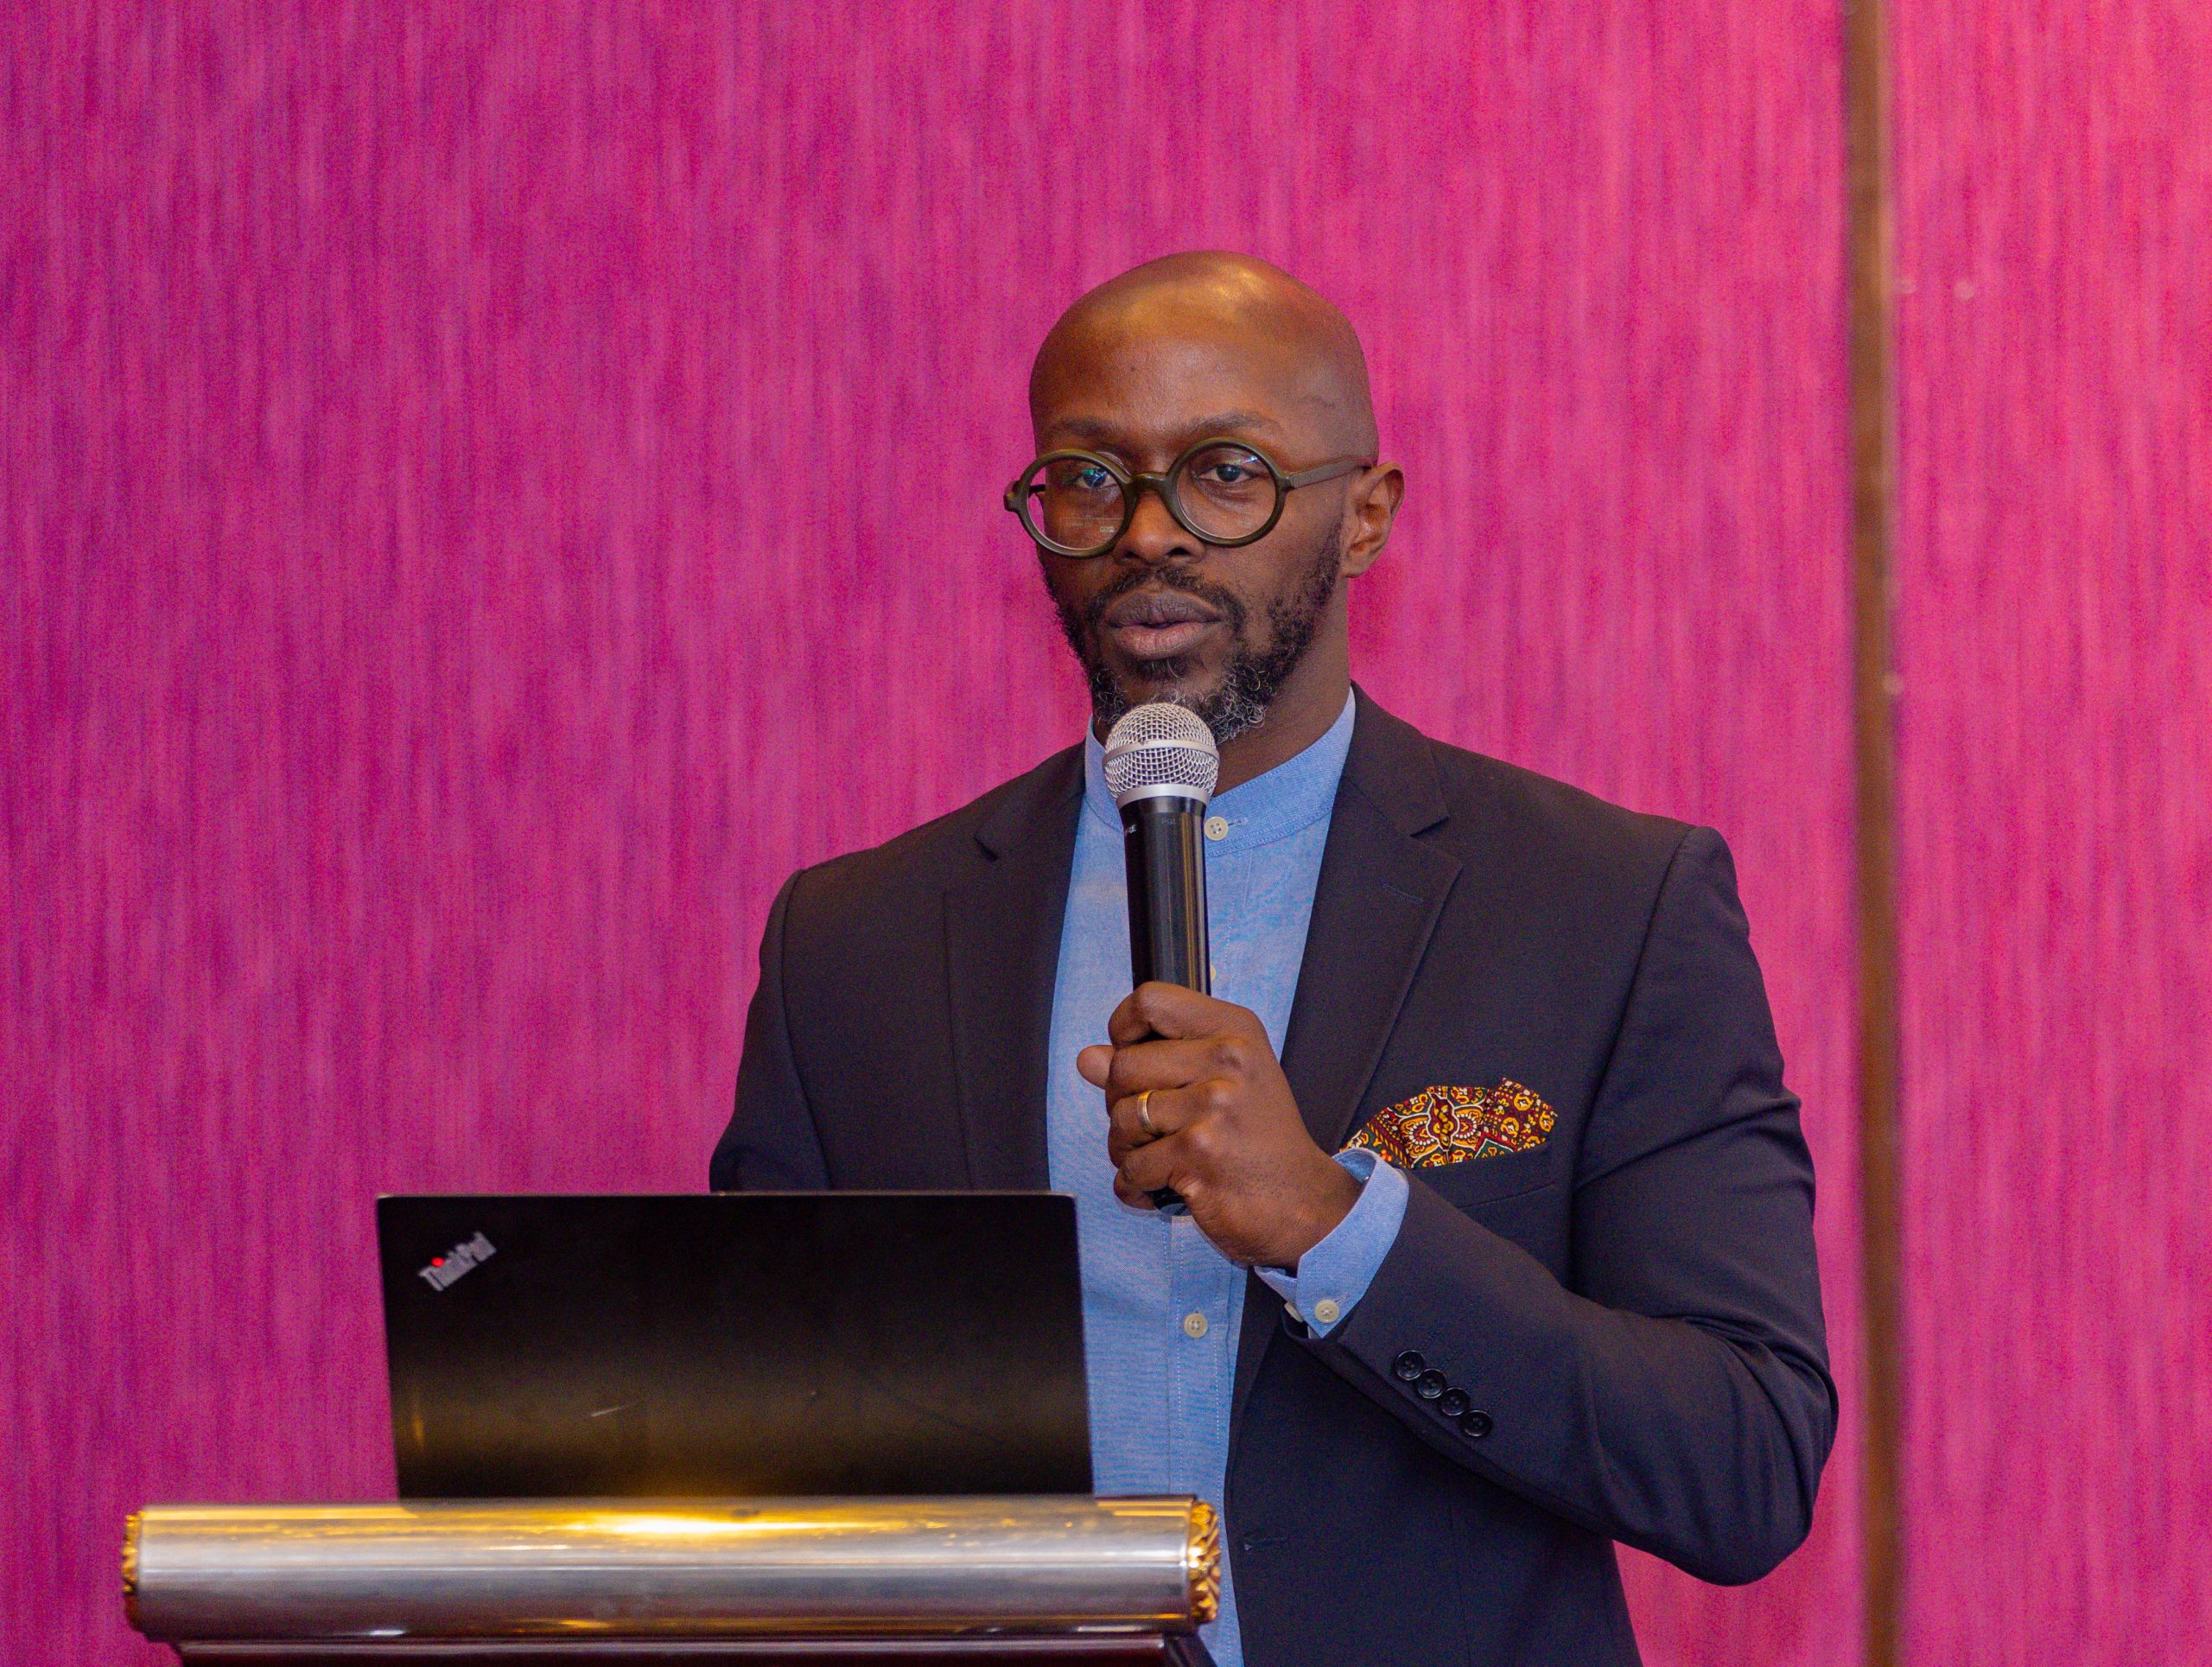
- Fidelis Muia – Kenya Bankers Association (KBA) Director of Technical Services at KBA and a veteran of Kenya’s payments evolution, from SWIFT to RTGS to cheque truncation.
- Marius Reitz – Luno General Manager for Africa at Luno, with an accounting and audit background and more than a decade in crypto.
- James Mabuti Mutua – Tether Lawyer, NYU graduate, former Parliamentary counsel who helped shepherd the virtual assets bill through the Finance Committee.
Other crucial voices
- George Mosomi – Tether Expansion Manager for Tether in Africa, with 12 years building scalable tech ventures across three continents.
- Jaine Mwai – Standard Chartered Chief Technology and Operations Officer at Standard Chartered Kenya, responsible for technology strategy and operations across East Africa.
- Andrew Barden – The Kenyan Wall Street CEO of TKWS and co‑founder of Wall Street Africa, bringing media, convening power, and deep fintech ecosystem knowledge.
- Apollo Sande – Luno Kenya Country Manager – Kenya at Luno, long‑time expansion lead across East Africa, and currently pursuing an MBA in Artificial Intelligence.
- Regulators and bankers Representatives from the Capital Markets Authority and major Kenyan banks (including Equity and KCB) who spoke candidly about risk, opportunity, and internal debates – often without wanting to be the headline.
It made the discussion feel like a closed‑door strategy session, not a conference panel.
From Barter to Bitcoin and Beyond
The session dug deeper than buzzwords. James offered a long‑view of money’s evolution:
“We began with barter trade… then we came to situations in which we had coins… then the banking industry developed enormously… [Then] the financial crisis… that’s why the Bitcoin white paper was released.”
His point was not to glorify crypto, but to normalise the idea that every leap in finance introduces new risks:
“All these innovations have their own inherent risks. The question is, how do we manage them… in a way that will enable innovation… inclusion… and growth of our financial structure?”
He then compared the future of payments to email:
“Imagine situations in which one is able to send money like you send an email… Communication has reached [that] threshold… The question is how we get financial services to that particular level in a responsible and compliant way.”
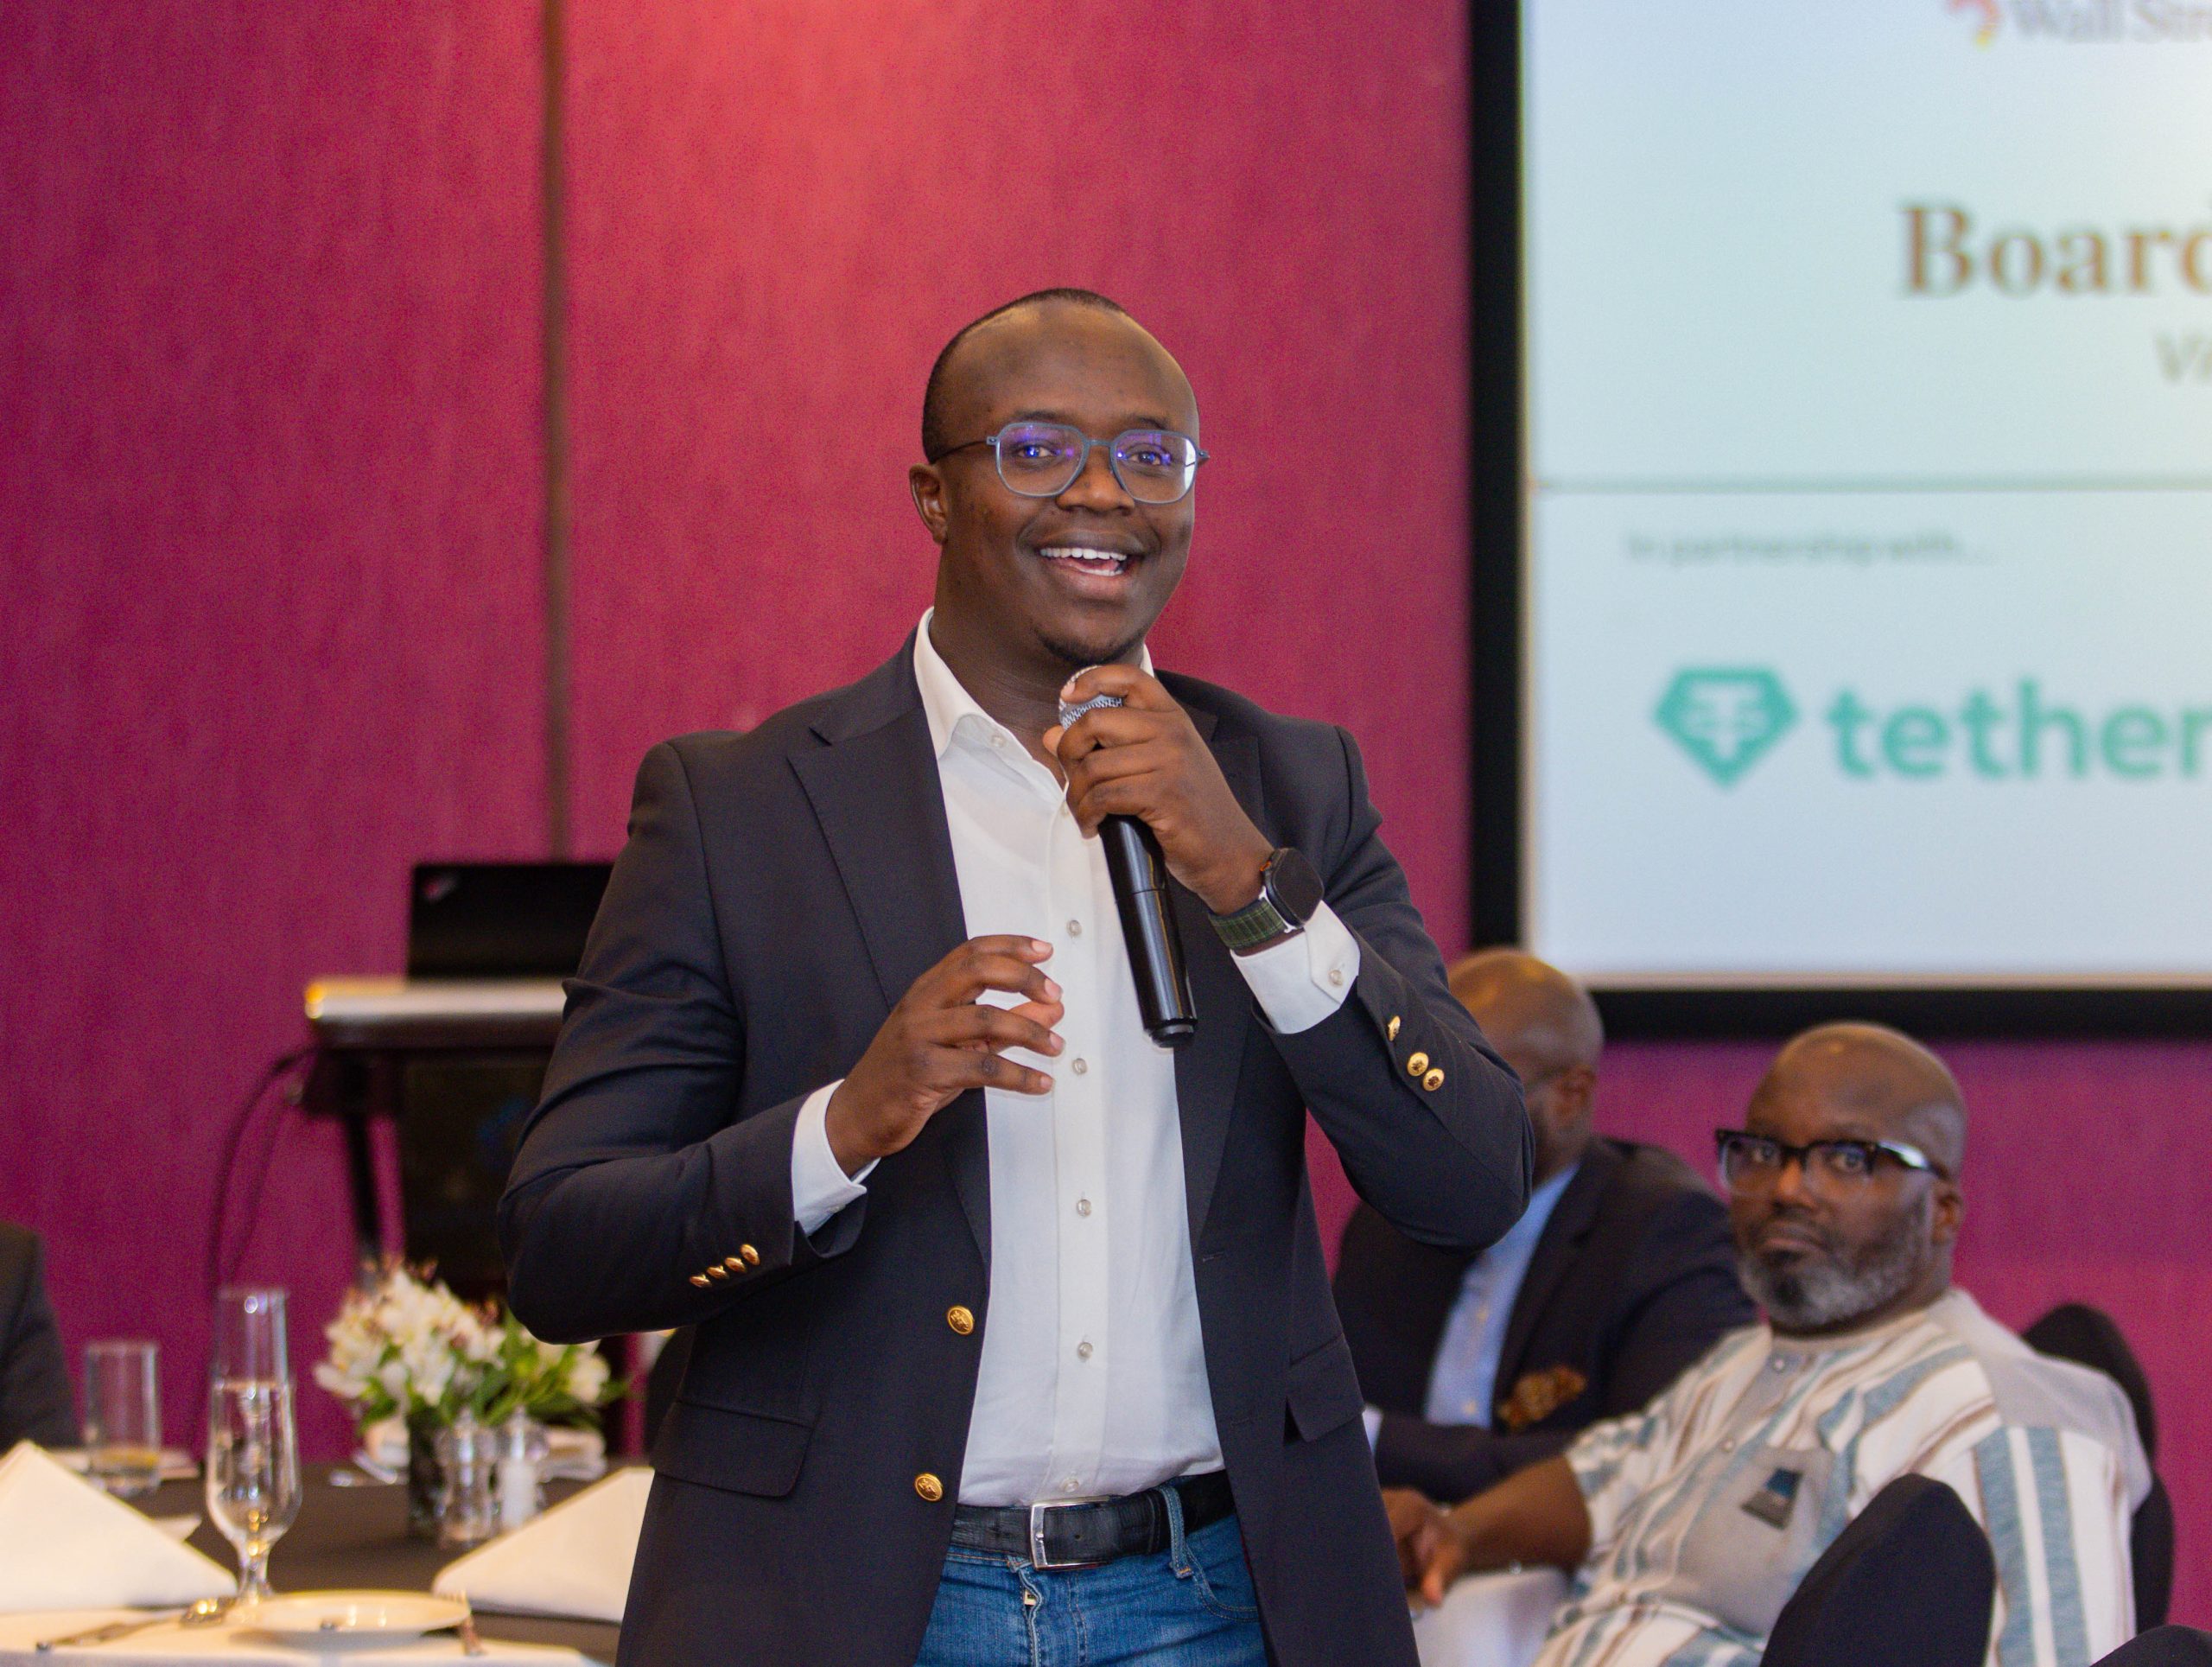
A participant involved in real‑world tokenization initiatives across the continent noted that we’re seeing the same pattern with digital assets and tokenization: rapid innovation first, regulatory frameworks catching up later. From tokenized real estate in Lagos to education bonds in South Africa and large tokenization commitments in Uganda, Africa’s asset base is quietly being pulled onto digital rails.
Tether, Stablecoins and the “Digital Dollar” for Africa
George told two stories that perfectly summarized why stablecoins matter in emerging markets.
First, as a Safaricom intern during the birth of M‑Pesa:
“They decided, before we give you money in your bank account, we want you to go to this random shop on Moi Avenue… That was the beginning… we were the first people to use M‑PESA in the market.”
Second, as a dollar‑paid employee of a US startup:
“I would get my salary… in US dollars, but the bank would not give me a favorable rate, so I would have to go withdraw my dollars… run down to my broker… convert the money into physical Kenya shillings, then go to another bank account, working carefully in the streets…”
That pain is the context for Tether’s proposition:
“Tether is the largest issuer of… USDT, which… is basically trying to give you access to the US dollar, which typically has been a hard challenge for people in emerging markets. So we’re solving liquidity challenges, we’re solving access challenges, we’re solving efficiency of transfer.”
The scale is hard to ignore:
- 184 billion USDT in circulation globally.
- 12 billion used daily in “cross border trade, online shopping, gig economy, remittance and payments, retail and commerce.”
Crucially, George emphasized partnership, not disintermediation:
“We believe that the banking industry is also looking at an opportunity to get… from the efficiencies that we provide… We want to listen to you. We want to innovate together… to ensure that everyone has this democratized access.”
Several bankers in the room admitted that their corporate and high‑net‑worth clients are already experimenting with stablecoins for trade, treasury, and hedging – often outside the banking system. The message between the lines: either banks design safe, compliant ways to participate, or volumes will continue moving on parallel rails.
Kenya’s VASP Act 2025: From “Don’t Touch” to “Design With”
For years, the Central Bank’s position on crypto was effectively “don’t touch.” Fidelis put it plainly:
“That same governor issued a circular to all banks telling them not to engage in anything to do with cryptocurrencies… For that reason, no bank has actually looked at that thing.”
At the same time, tax authorities were trying to tax virtual assets before the law defined them, forcing KBA to ask basic questions:
“We went to KRA and asked them… what is a virtual asset… because no law in Kenya actually described it… How are you taxing something that has not been described?”
The VASP Act, 2025, changes that by:
- Creating a licensing and supervisory framework for VASPs.
- Treating virtual assets as part of the financial system with explicit AML/CFT expectations.
- Requiring local incorporation, fit‑and‑proper management, prudential safeguards, and reporting.
Fidelis highlighted how unusual this moment is for Kenya:
“Previously, a lot of things happened, and then the regulator comes to put order… Here we have… a scenario where there is a regulation, and we are now coming to see what it is we can do with the regulation.”

James zoomed out to the African landscape, describing three approaches firms are using:
- Go where clarity exists – South Africa and Mauritius, which amended existing laws rather than waiting for a “perfect” new regime, leading to hundreds of firms registering with regulators.
- The “stablecoin sandwich” – where licensed PSPs in two countries anchor the ends, while a stablecoin clears value in the middle, making cross‑border transactions almost invisible to traditional rails.
- Hybrid structures – with a core entity in a clear jurisdiction and local entities focused on compliance, marketing, and regulator engagement.
His warning:
“Innovation does not necessarily wait for regulation… There’s already demand… firms have realized that adoption is going to be there, whether the regulator is ready… or not.”
A representative from the Capital Markets Authority added an important counter‑narrative:
“We’ve had a lot of [virtual] asset service providers… come to the regulator as backers… like 50 firms have come to the authority to ask for regulation… That just shows they are trying to… minimize the risk by identifying themselves and saying, ‘Here we are.’”
In other words, this is not a cat‑and‑mouse game. Many serious players want to be supervised – and see Kenya as the place to do it.
Banks On‑Chain: Risk, Opportunity and Lessons from Across Africa
Ali added a macro layer to the conversation:
“Africa’s 100 billion digital asset transformation is unfolding in Lagos, Nairobi, Joburg… stablecoins are not speculation anymore… They are solving a currency crisis. 70% of African nations face Forex shortages… The critical question now isn’t whether tokenization will happen, it’s who will capture the value.”
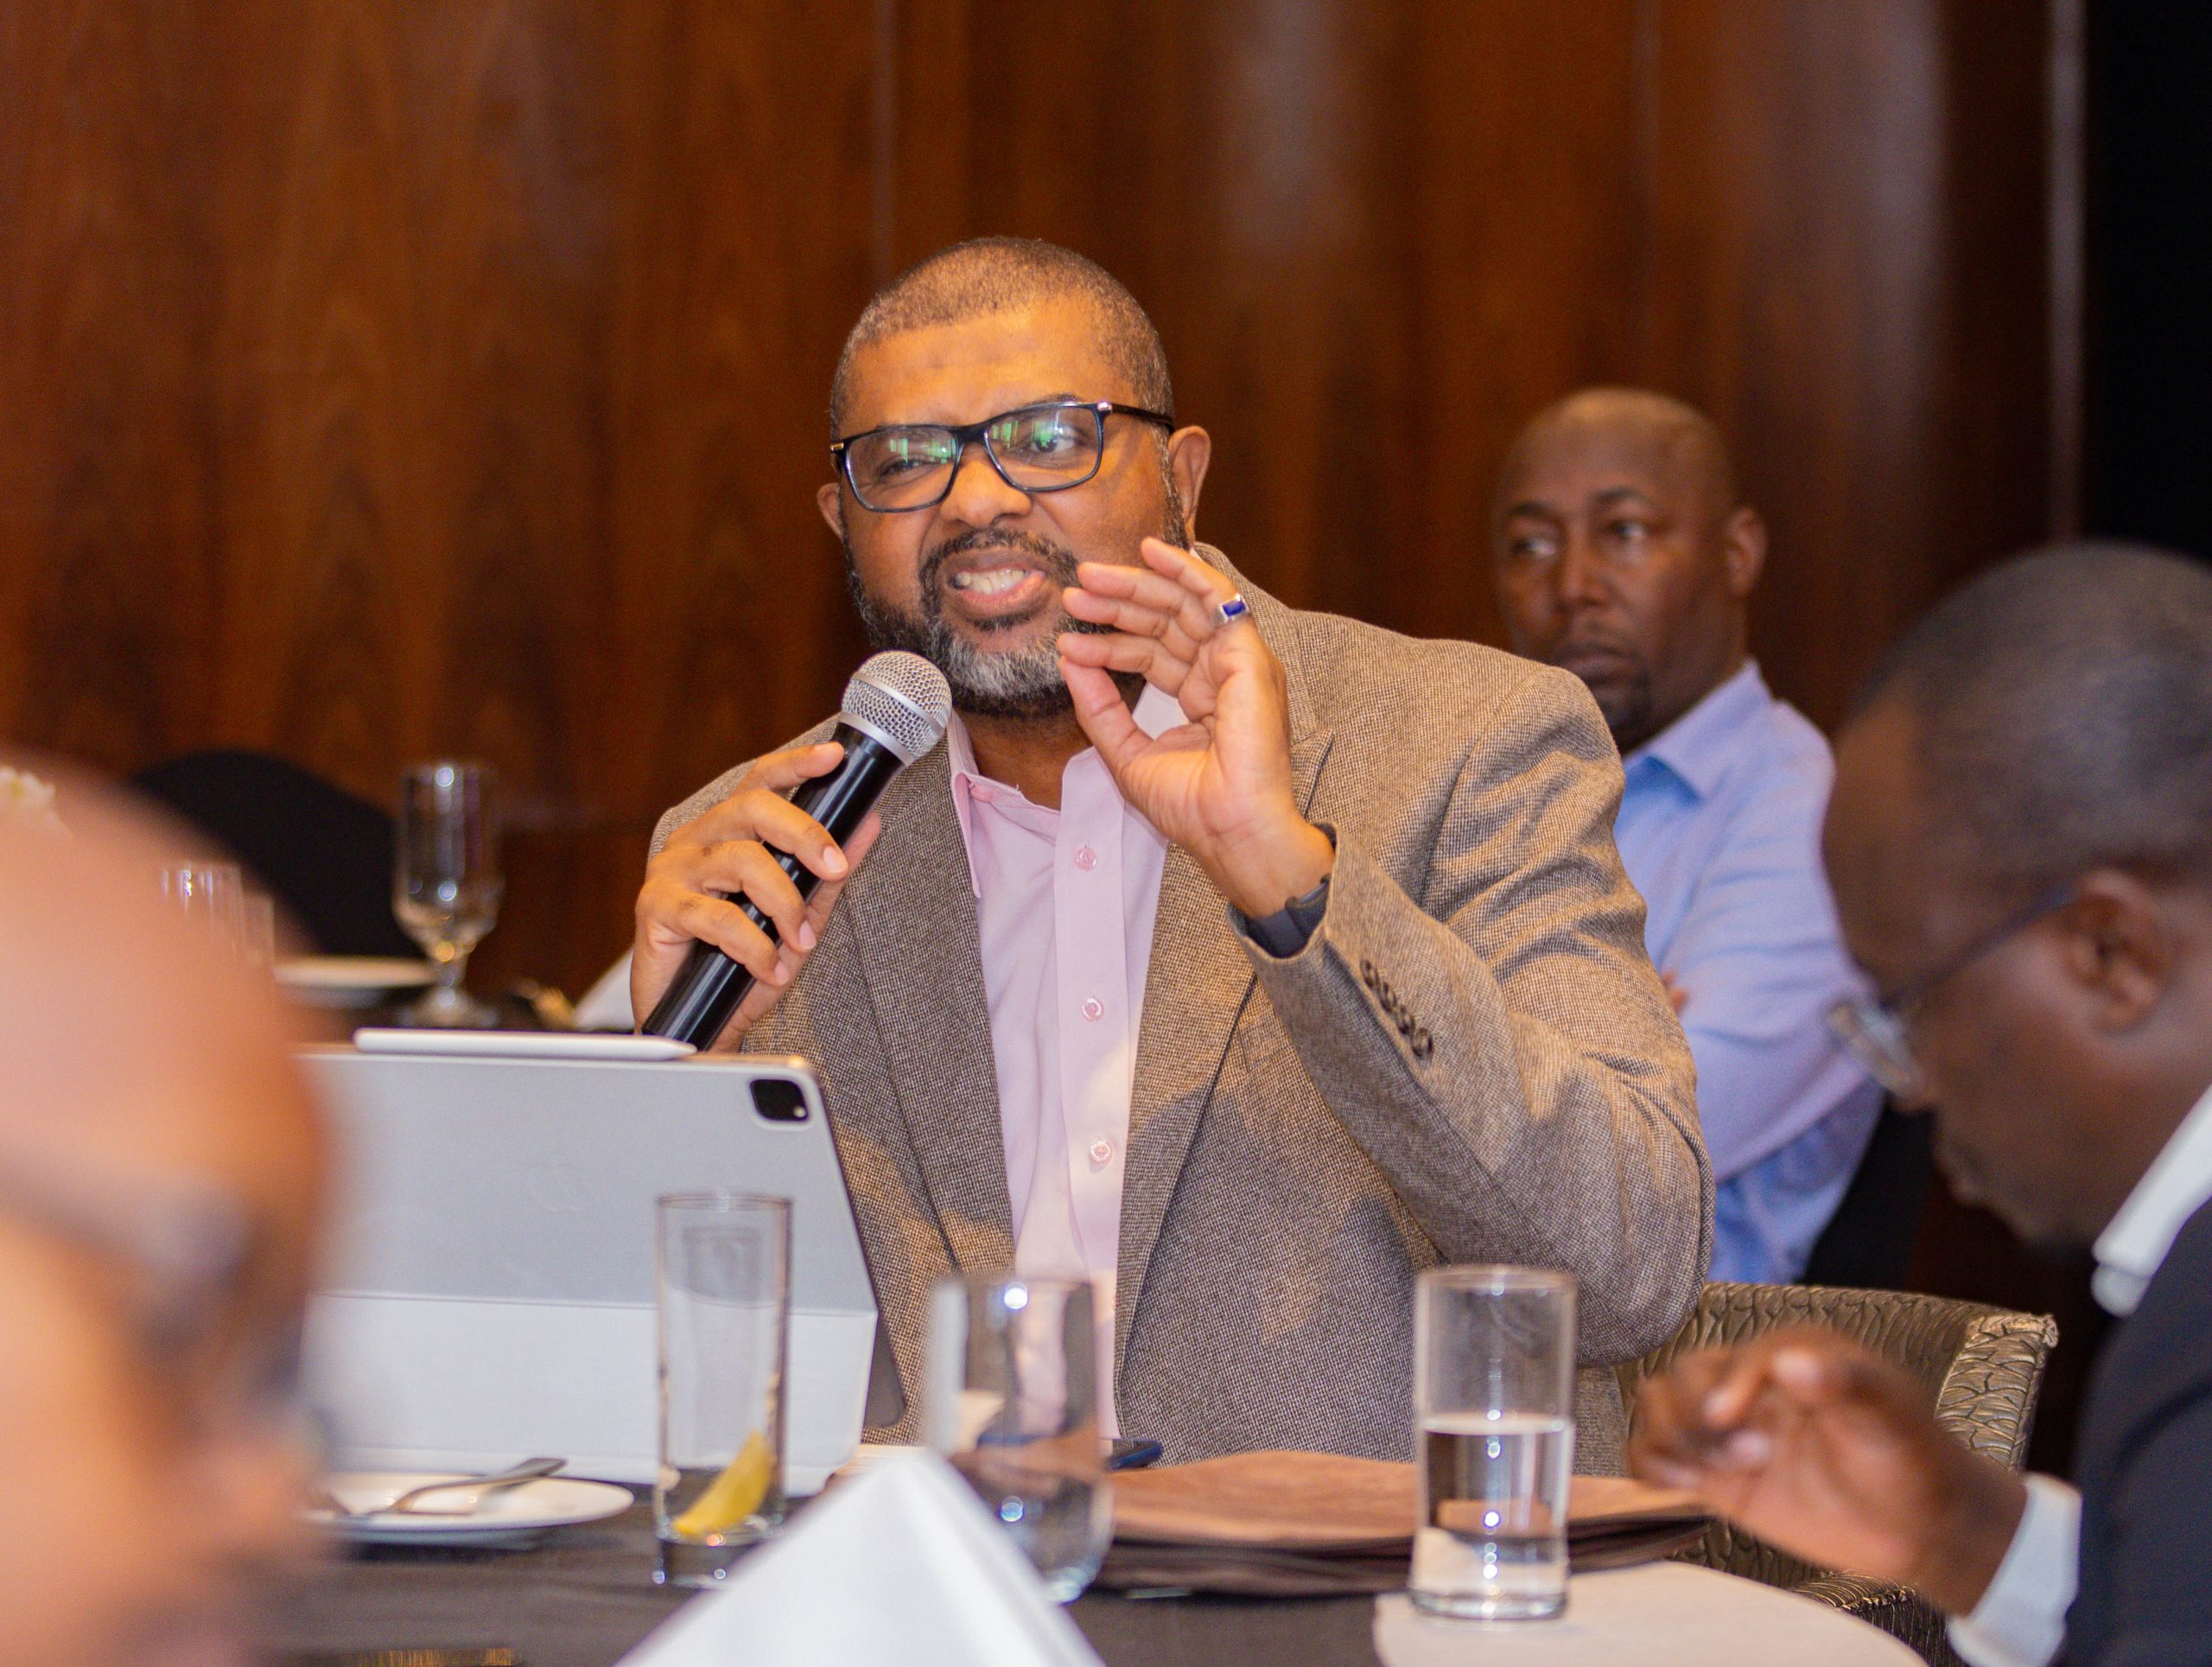
Marius used South Africa as a live case study for pragmatic, risk‑aware regulation. On risk:
“All financial systems carry risk. You cannot eliminate all risk… The messaging apps we use are being used to facilitate crimes on a daily basis. They’re not being banned because they have a net positive effect to society…”
South Africa’s first regulatory phase focused on three pillars:
- AML/CFT – FIC registration, on‑site inspections, and detailed scrutiny of RMCPs, KYC, sanctions screening and risk refresh cycles.
- Consumer Protection – a formal complaints channel and independent dispute resolution against licensed exchanges.
- Fit and Proper – ensuring founders and directors can actually run a financial services business and safeguard client funds and data.
Back to Kenya, he highlighted a consumer‑protection blind spot:
“Most Kenyans… access crypto assets [today] through peer‑to‑peer platforms… or underground chat rooms… and it introduces a tremendous amount of risk… I’ve heard horror stories… people being scammed… thousands of dollars.”
His proposed interim fix:
“Allow an interim regime where cryptocurrency businesses that are onshore, locally incorporated with local directors… registered, perhaps first on a voluntary basis with the FRC… and willing to share data… [can] engage with commercial banks.”
On the opportunity side, examples from across Africa are already emerging:
- Absa – with an institutional crypto custody offering and a gold‑backed stablecoin.
- Standard Bank – acting as custodian for a rand‑denominated stablecoin, after working through risk committees and governance.
- Tokenization projects – from property in Lagos to education bonds and resource‑backed assets, shifting “stranded” assets onto programmable rails.
A representative working on tokenization in East Africa summed it up:
“This is not a proof‑of‑concept phase anymore – this is infrastructure in the making.”
Collaboration, Not Confrontation
One of the most encouraging aspects of the roundtable was how often people returned to collaboration.
Fidelis described KBA’s deep involvement in both policy and infrastructure:
- Advising CMA and Treasury during early virtual asset policy discussions.
- Sitting on CBK’s technical working group revising the National Payment System to recognise new classes of payment providers.
He explained why a coordinated banking approach matters:
“Can we all move in lockstep, rather than everybody do what they think they should be doing and create chaos?… If we all are in agreement… then it becomes easy… for the customers to understand… and for us to align and actually realize the benefits.”
The CMA representative echoed that regulators are already meeting the industry halfway:
“Kenya has a jurisdiction [where] people with good intentions… want to make this market work… It’s incumbent upon the regulator now to have regulation that is bespoke to this jurisdiction, with the players being ready and offering an open door.”
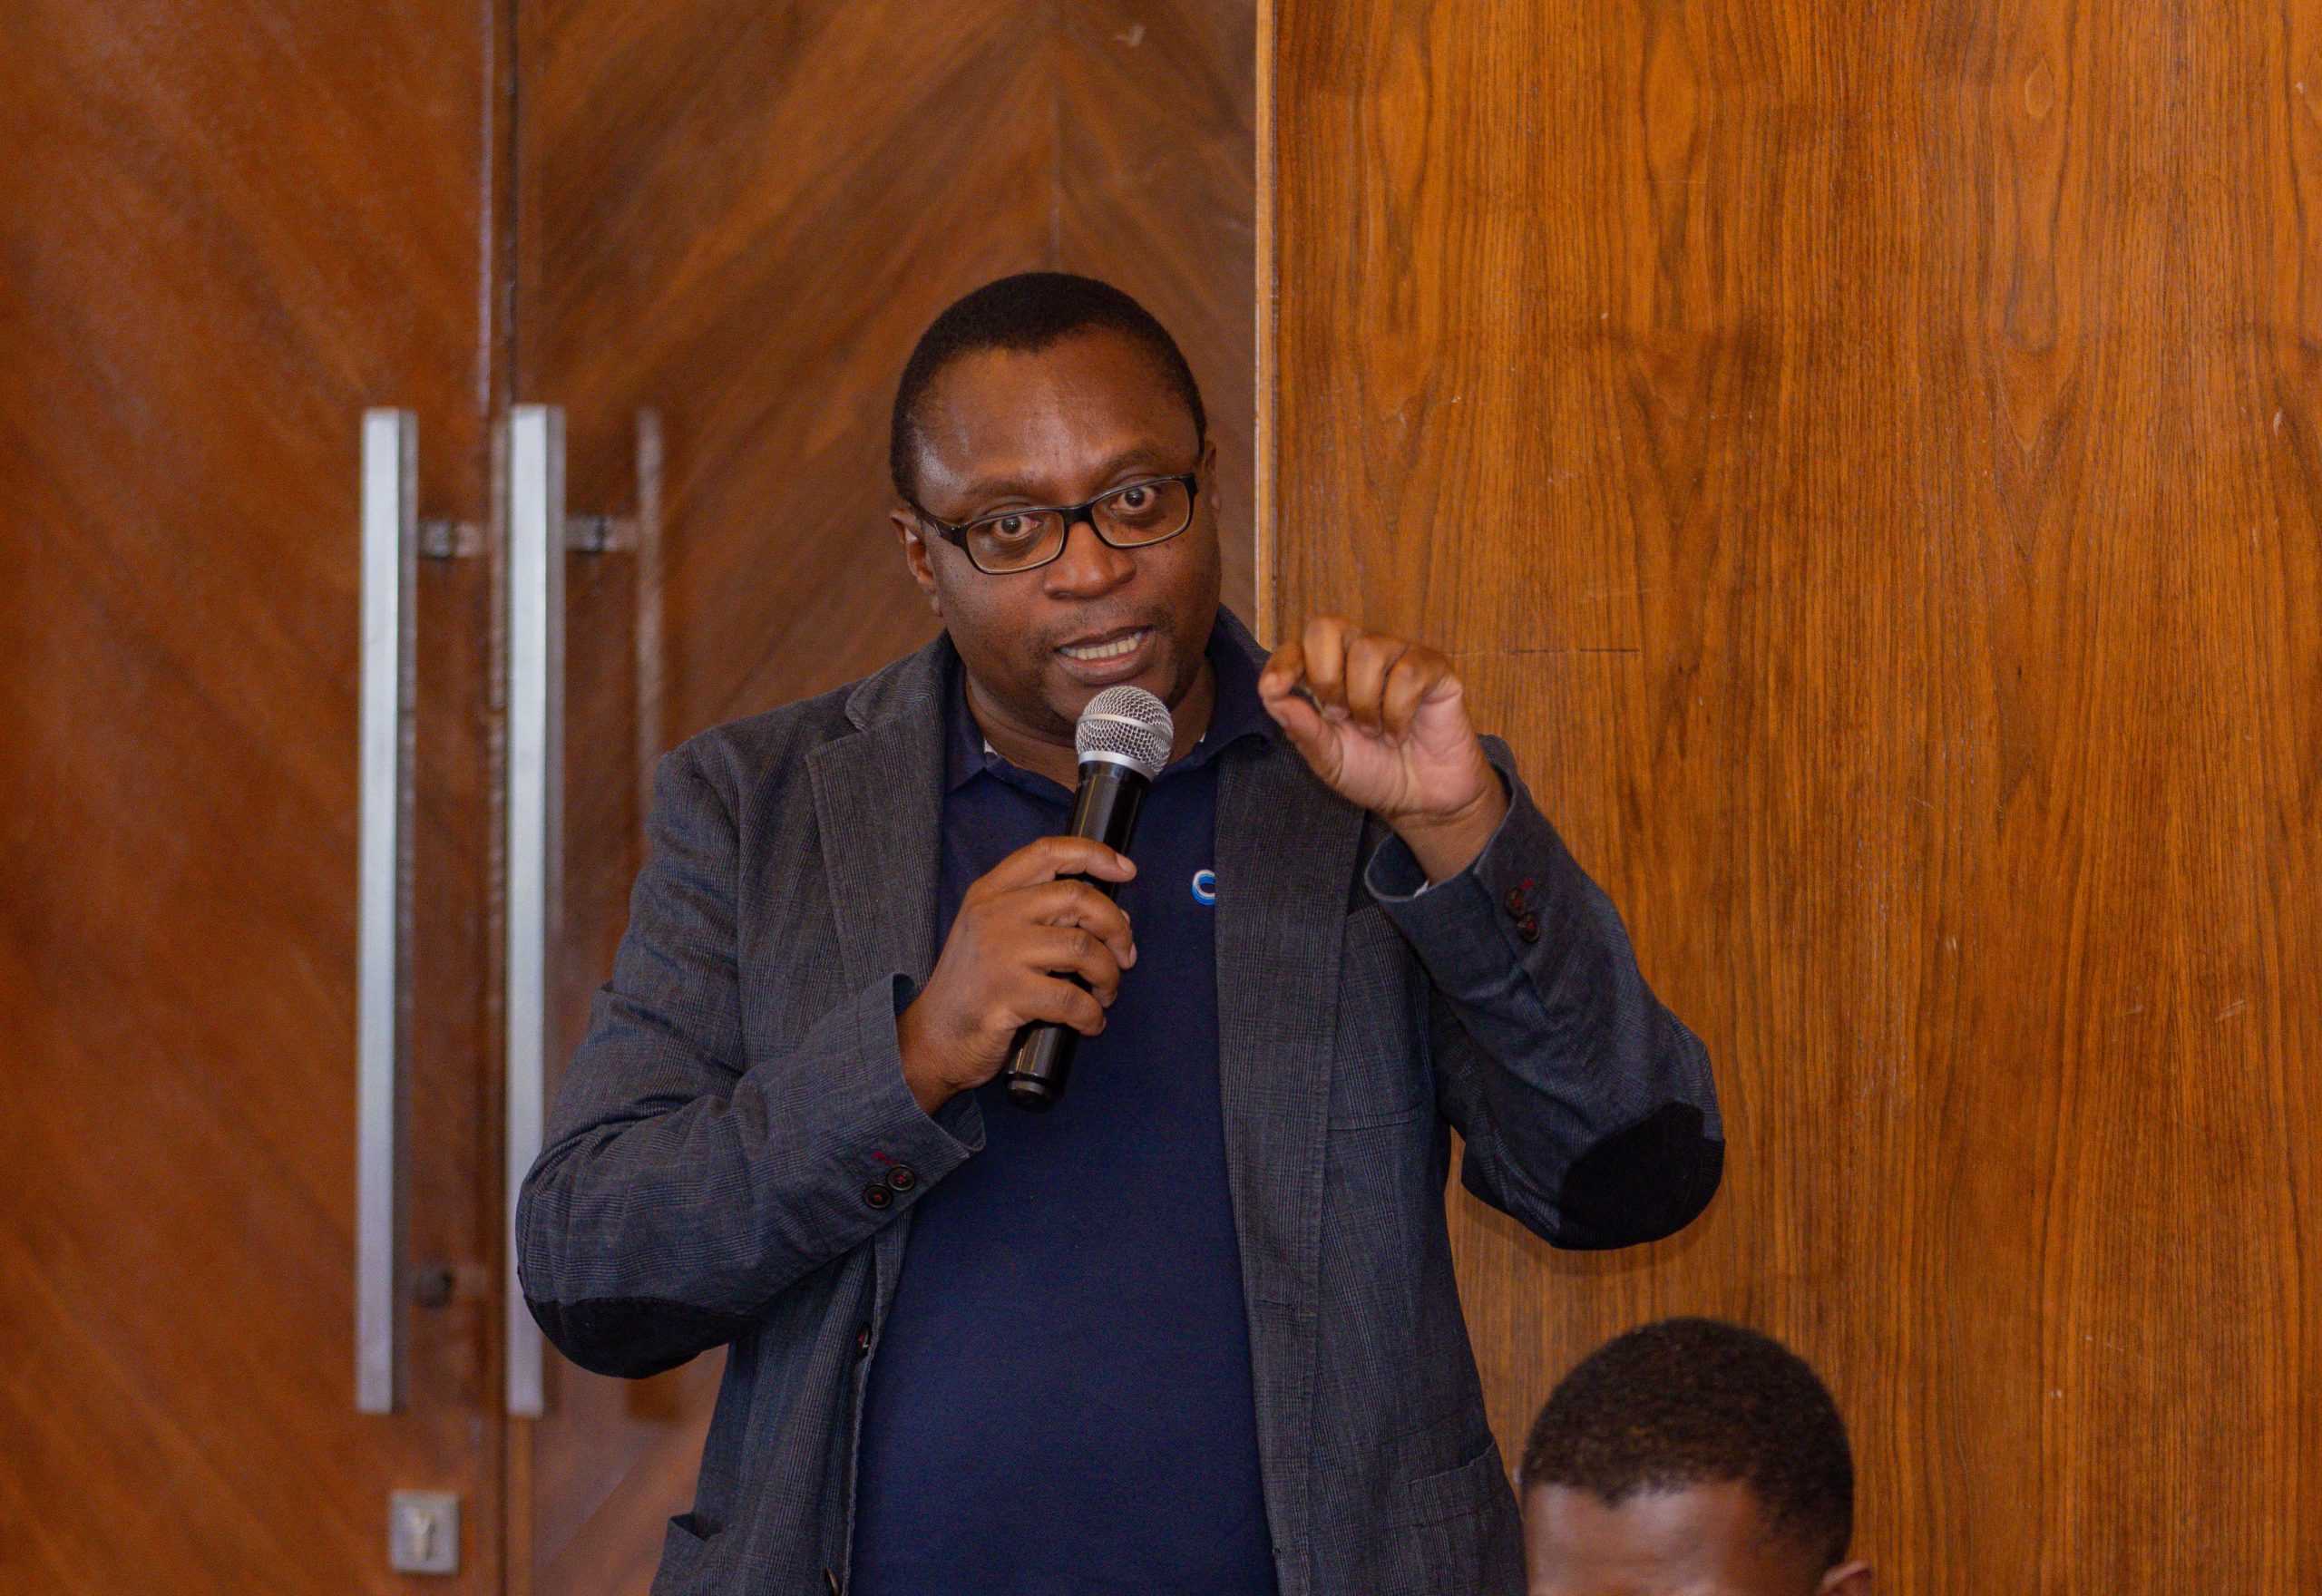
Apollo offered a very practical template for collaboration:
“Three years ago… Luno flew down our Head of Compliance from Johannesburg… and we took [banks] through our RMCP… to paint the picture that this is actually incredibly possible within the crypto industry.”
He showed how far such partnerships can go:
“In South Africa… Discovery Bank [lets customers] ‘Buy Bitcoin with Luno’ inside the banking app… Two weeks ago, [we] launched – in partnership with Sanlam – ZARP, a proper institution‑grade stablecoin… one‑to‑one, fully backed by the ZAR.”
His conclusion:
“The quickest way for that knowledge transfer and to get that sweet spot is partnership.”
Several bankers and a representative from a major digital exchange project suggested extending this collaborative model to Saccos, MFIs, and regional banks that are already seeing crypto‑linked flows but lack the understanding and tools to respond.
Concrete Action Items from the Roundtable
By the end, the room had converged on three clear, tangible action items:
- Compliance Workshop for KBA and Regulators Luno committed to organising a hands‑on workshop for KBA member banks and relevant regulators:
- Sharing South African & Regional Best Practices Luno will share detailed materials and engagement models from South Africa, Malaysia and other markets – covering interim licensing regimes, bank‑VASPs relationships, risk frameworks, and supervisory data‑sharing.
- KBA‑Led Unified Banking Approach to Virtual Assets KBA will convene member banks to build a step‑by‑step, unified approach to virtual assets and to craft a coherent industry position for regulators:
Several participants also suggested pulling Saccos and MFIs into future conversations, given the crypto activity already touching their customer bases.
My 7 Personal Takeaways
- Regulation Is Finally a Platform, Not a Pause Button The VASP Act 2025 moves Kenya from warnings and informal circulars into a structured regime that banks, fintechs and regulators can actually build on. As Fidelis said, this time the regulators “want to put an orderly start to a process,” not just arrive after the chaos.
- Stablecoins Are Already Doing Real Work for Africans George’s personal stories, combined with Tether’s numbers – 184 billion USDT outstanding and 12 billion used daily – make it clear that stablecoins have become a functional “digital dollar” rail for trade, gig work, remittances, and online commerce in markets like ours.
- If Kenyan Banks Don’t Engage, Parallel Rails Will Flourish Anyway James’ “stablecoin sandwich” and Marius’ P2P horror stories show that customers will find ways to access virtual assets – whether or not local banks and regulators are in the loop. The real risk is not “crypto happening,” but “crypto happening without Kenyan oversight or participation.”
- Risk Can Be Managed – If We’re Willing to Use the Right Tools South Africa’s approach – FIC registration, on‑site inspections, consumer‑complaint channels, and fit‑and‑proper tests – shows that crypto risk can be brought into familiar regulatory toolkits. The technology actually offers more visibility than cash, if we choose to use it.
- Tokenization Is About Unlocking Stranded African Value The conversation around tokenized property, education bonds, and resource‑backed instruments highlighted a much bigger story: tokenization could mobilise assets traditional finance has left stranded for decades. For Kenya, that means thinking beyond mere coin trading to re‑imagining how we finance everything from housing to agriculture.
- Kenya’s Regulatory and Banking Community Is More Open Than Its Reputation Suggests CMA’s acknowledgement that 50+ firms have proactively approached them for regulation, KBA’s call for moving “in lockstep,” and banks privately admitting they’re seeing stablecoin flows tells me the narrative has shifted from “ban or ignore” to “how do we do this properly?”
- 2026 Is a Genuine Inflection Point – Our Kodak Moment With the VASP Act in force, draft regulations imminent, Africa‑wide tokenization experiments underway, and global institutions going on‑chain, this feels like a Kodak moment for Kenyan finance. We can either cling to legacy rails and watch value leak out to parallel systems, or intentionally design a future where banks, fintechs, regulators and innovators share digital rails and responsibilities.
Where We Go from Here
Sitting in that room at the Capital Club – listening to George’s Safaricom and FX stories, James’ behind‑the‑scenes Parliament narrative, Marius’ regulatory scars, Fidelis’ candid reflections on CBK and KBA, the CMA’s openness, tokenization pioneers, bankers’ cautious curiosity, and Apollo’s very practical partnership offers – it was hard not to feel that Kenya is standing at the edge of its next big digital finance chapter.
We now have a law. The regulations are coming. The demand is already here – from Gen‑Z traders and P2P communities, to merchants, SMEs, corporates, and institutional investors. The real question is whether we’ll design an integrated system where banks, fintechs, regulators and innovators share rails and responsibilities, or allow innovation and risk to continue running in the shadows.
If you’re in banking, policy, fintech, or just deeply interested in Kenya’s digital future, what does a responsible, opportunity‑driven sweet spot look like to you in this new virtual assets era? Share your thoughts in the comments, pass this along to someone who should be in the next room like this, and stay tuned – I’ll be unpacking more of this in an upcoming podcast episode based on the full recording from the TKWS Board of Trailblazers roundtable.
The Author


No Comment